The Housing Market Is on Solid Ground, Even with More Foreclosures

The Housing Market Is on Solid Ground, Even with More Foreclosures
It’s been nearly two decades since the 2008 housing crash, but the word “foreclosure” can still make people uneasy. And if you’re planning a move, you may be wondering if more foreclosures will flood the market with homes for sale – especially if you’ve seen the headlines lately.
Buyers may be hoping for a rush of bargains. Sellers may be bracing for more competition. The latest data points to neither, and knowing why can help you plan your next move with confidence.
A Modest Rise from a Low Starting Point
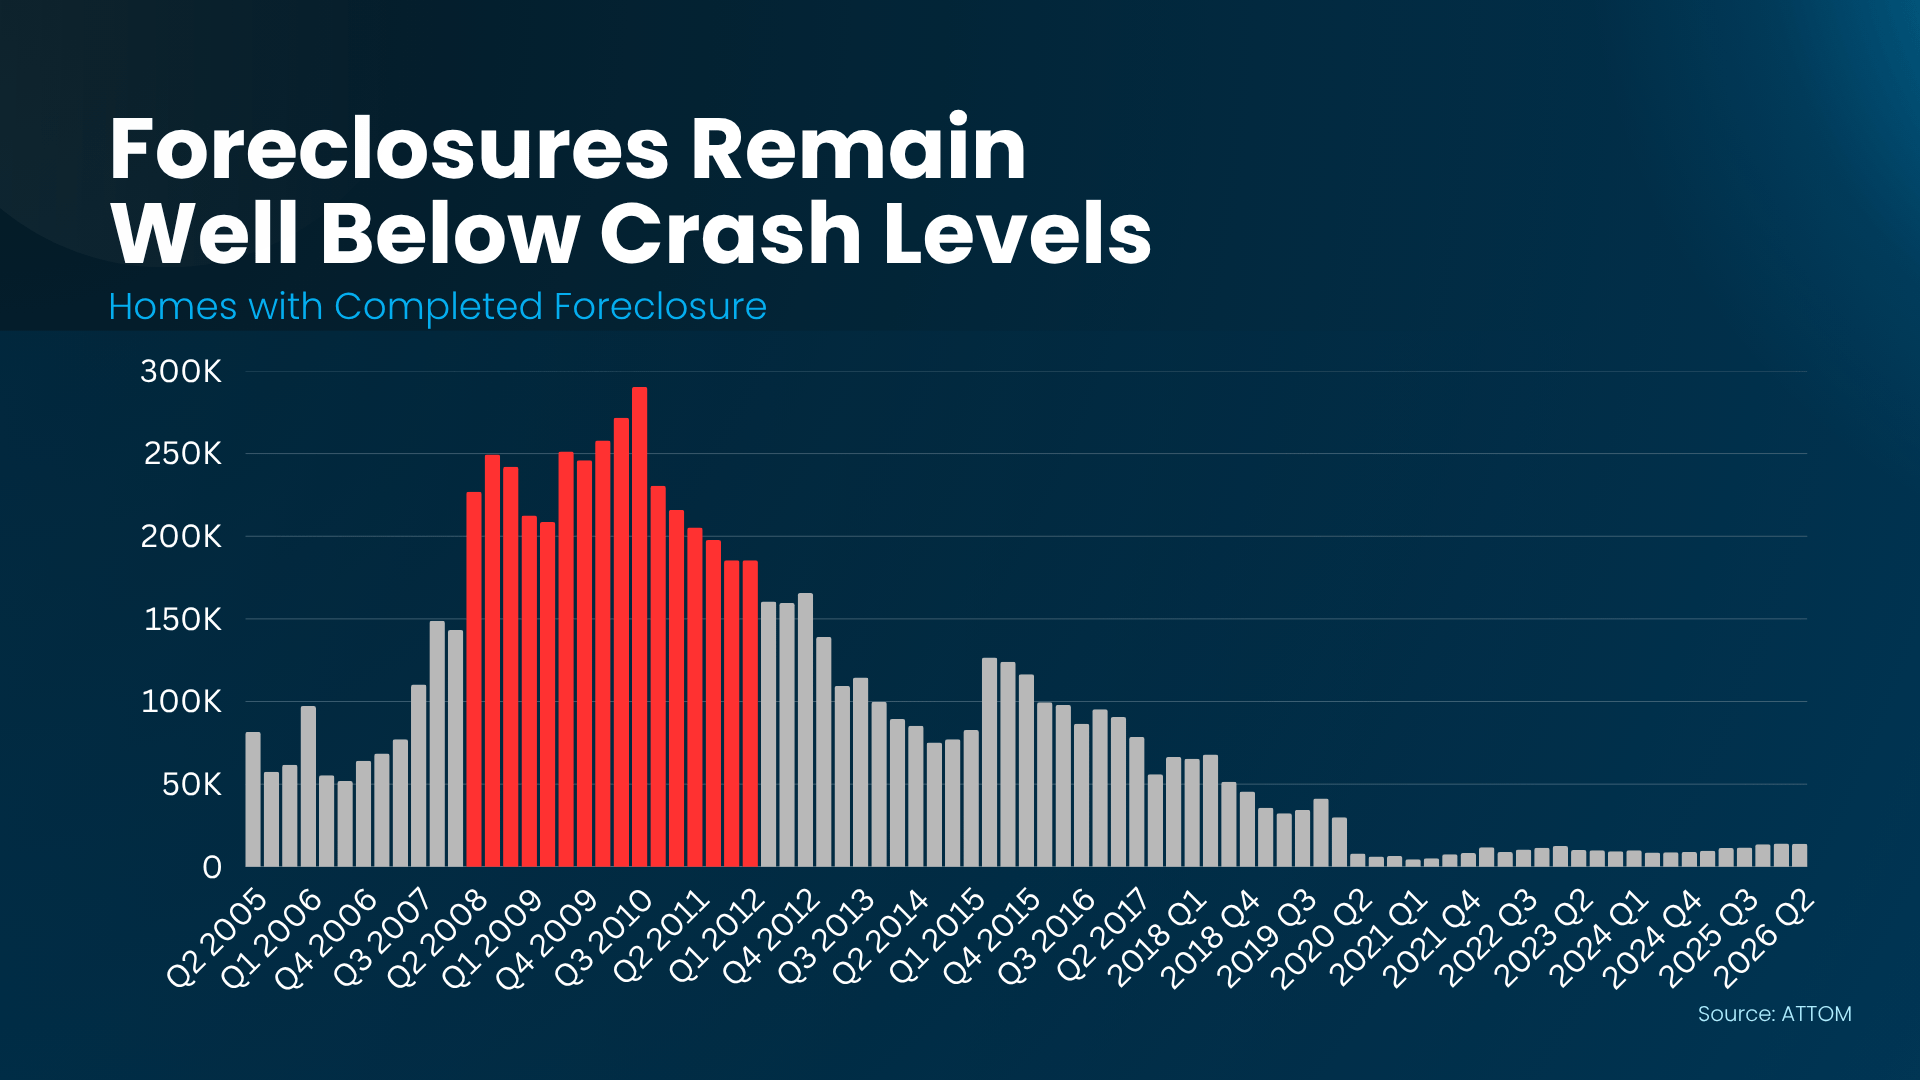
Completed foreclosures are up 33% from last year, according to ATTOM. That sounds like a big leap, but context helps.
Even with that increase, foreclosures are still about 26% below where they were in the first half of 2020.
Zoom out further, and today’s activity is a small fraction of what the market saw during the 2008 crash. Lenders completed about 28,000 foreclosures in the first half of 2026, according to ATTOM. Compare that to the crash years in red, when lenders often completed more than 200,000 in the span of a few months (see graph below):
Experts say today’s numbers reflect a housing market that’s still in good shape. As Rob Barber, CEO at ATTOM, explains:
“While some homeowners are still facing financial challenges, overall foreclosure volumes remain well below historical norms and the broader housing market continues to demonstrate resilience.”
And here’s why we can absorb the slight uptick in foreclosures we are seeing.
Homes for Sale Are Back in a Balanced Range
During the crash, a lot of homeowners either lost their homes to foreclosure or were forced to sell, which left the market overwhelmed with houses for sale. That isn’t happening now.
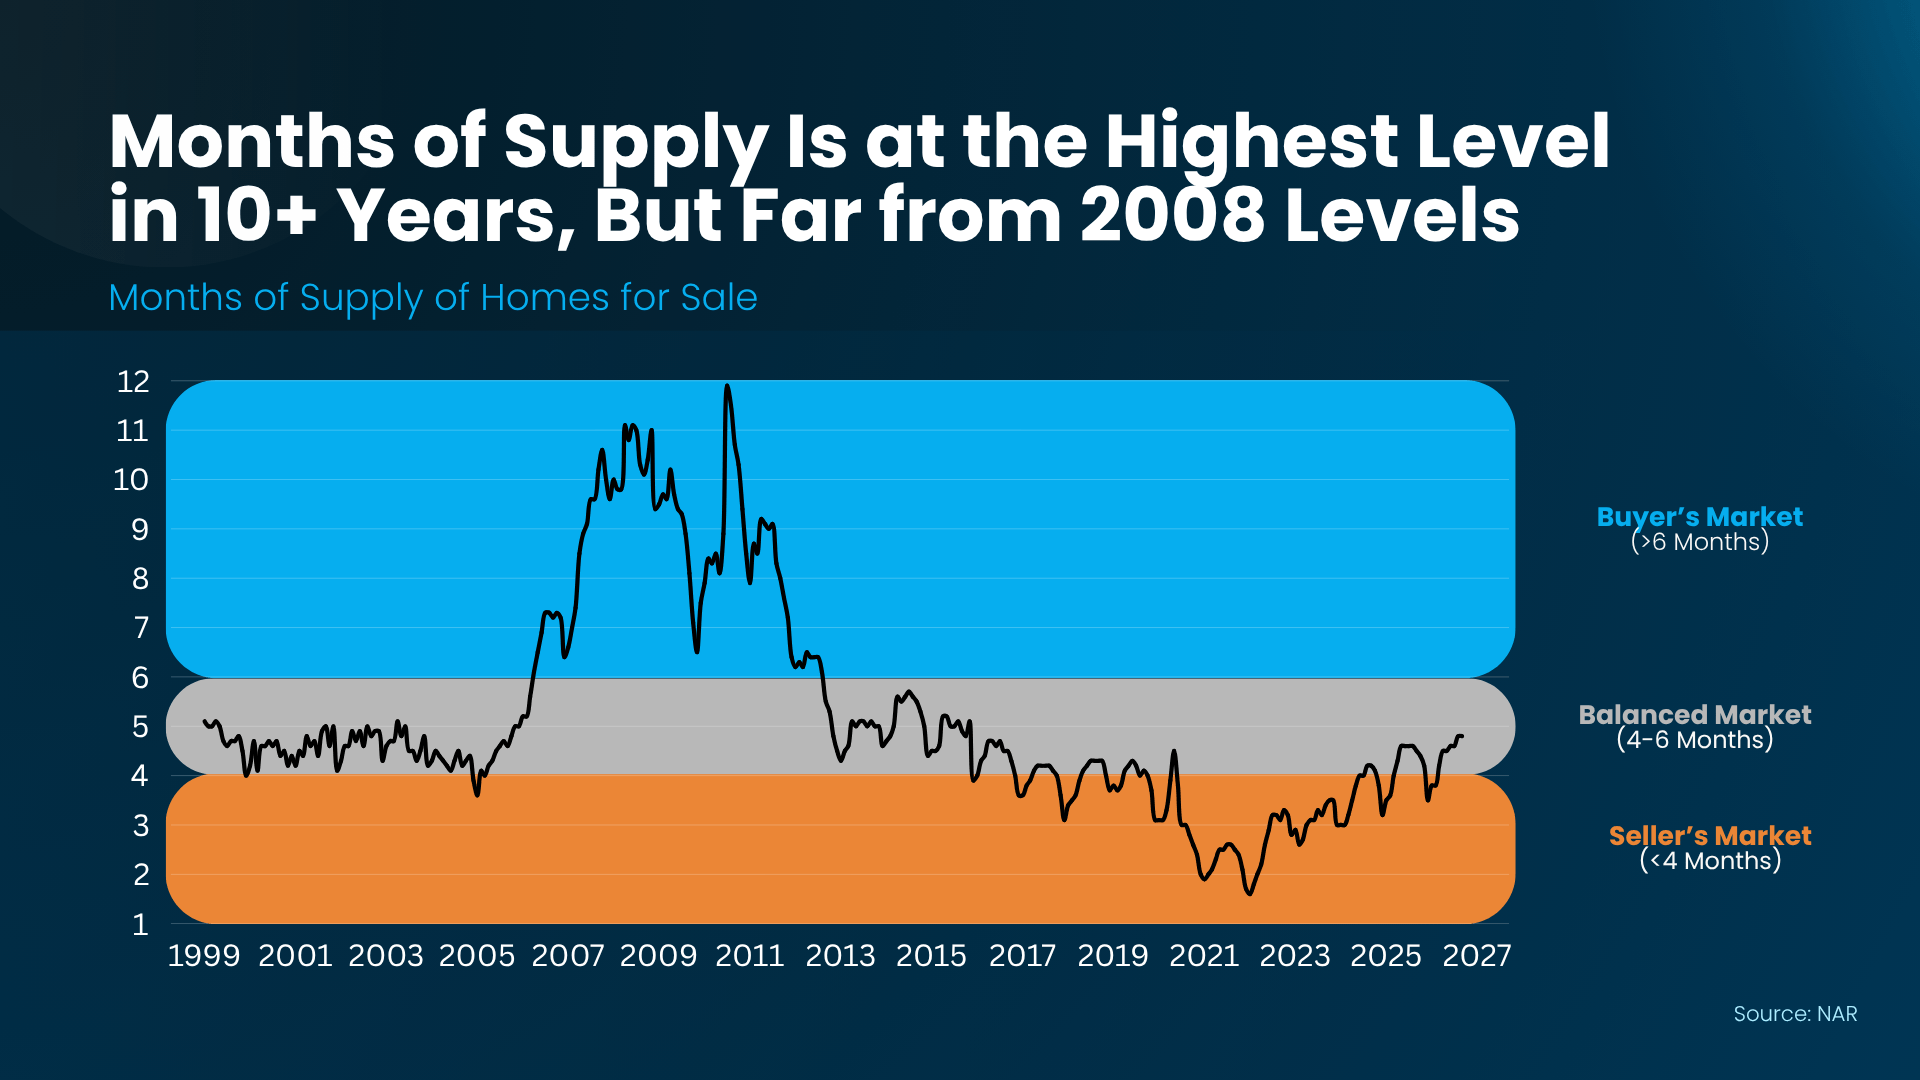
One way to see this is through months’ supply, which measures how long it would take to sell every home on the market at the current pace. Four to six months is considered balanced.
Right now, it’s about 4.8 months, according to the National Association of Realtors (NAR). That’s pretty well-balanced, and less than half of where it peaked around the last crash (see graph below):
If foreclosures were really surging, you’d see it in the number of homes for sale. As Logan Mohtashami, Lead Analyst at HousingWire, explains:
“. . . a surge of actual foreclosures in 2026 would have easily put the inventory data much higher in 2026.”
Equity Gives Today’s Homeowners Options
Equity is a big reason there’s no surge of distressed sales. Data from the Census Bureau and ATTOM shows nearly two in three homeowners have paid off their mortgage or have more than 50% equity. And Cotality says the average homeowner has about $310,000 in equity.
If a homeowner with equity hits a rough patch, they can usually sell their house, pay off the loan, and walk away with money in their pocket instead of facing foreclosure. That’s an option many people didn’t have during the crash. According to HousingWire, nearly one in four homes were underwater back in 2010.
Being underwater means owing more on your mortgage than your home is worth, which makes selling a lot harder. Today, just 2% of homeowners are considered seriously underwater (see graph below):
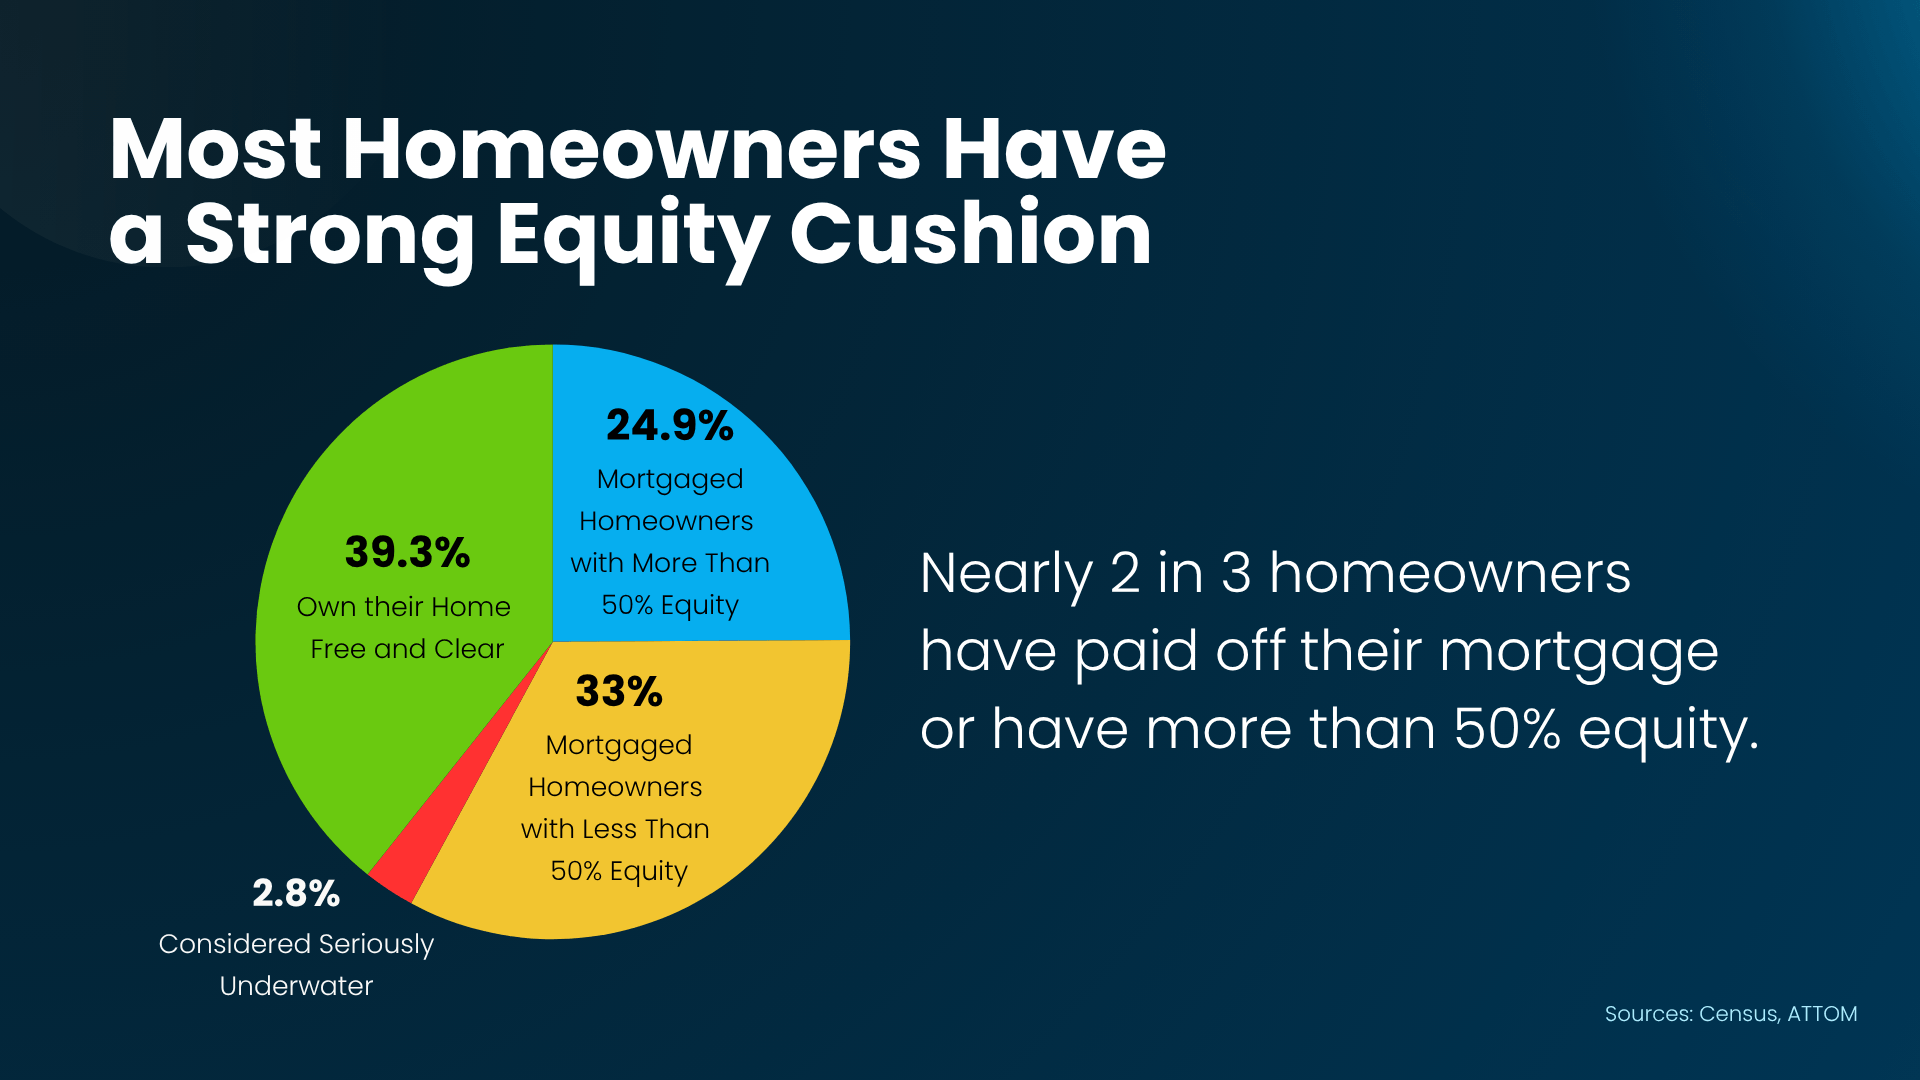
Not every homeowner has that kind of equity, but most do, and that’s what puts a ceiling on how high foreclosures can go.
Bottom Line
If rising foreclosures have you questioning where the housing market is headed, the data says it’s in good shape. The supply of homes for sale is balanced, and most homeowners have plenty of equity.
Have questions about what you’re seeing online, our local market, or about how much equity you have? Let’s talk.
Categories
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "